Occupational Rights in Pregnancy
Occupational Health and Adjustment to Work Duties:
You should contact your Line Manager as soon as reasonably possible so they can assess how pregnancy will impact your duties and what adjustments should be made to keep you and your baby safe. They will be able to refer you to Occupational Health if required. It is your employer’s responsibility to find locum cover if you are unable to undertake on-calls or nights. It is your right, from 28 weeks of pregnancy, to decline to undertake on-call or night shifts. You do not need to “swap” or “make up” for this in any way. If you cannot continue in your current post and no alternative duties can be found for you, you can be “suspended” on full pay (not because you’ve done anything wrong, this won’t count against you or your fitness to practice and just counts as TOOT).
The above also applies to allow you to successfully breastfeed your baby and your duties should be altered to allow you to feed your baby or pump in comfort and privacy.
Attending appointments:
As a pregnant employee, you are entitled to paid time off to attend antenatal appointments, inclusive of medical appointments, parenting classes, pregnancy yoga etc as long as they are advised by a registered medical professional.
Partners of pregnant people are allowed paid time off for 2 appointments, each lasting 6.5hrs maximum. Any other appointments will need to be covered by annual leave, unpaid leave or shift swaps.
Employment Rights:
You continue to be eligible to receive pay rises (e.g. uplifts from industrial action or in new tax years). You will also accrue annual/bank holiday leave and you can use this to extend your parental leave so you still receive pay. You have a right to return to work after your parental leave.
Useful links:
Maternity Leave
Your To Do List:
You must notify your employer in writing before the end of the 15th week before the baby’s due date of your intention to take maternity leave:
Provide the date from which you want to take leave (anytime from the 11th week before baby is due)
Confirm that you intend to return to NHS employment for a minimum of three months after leave (if your training contract ends before the 3-month period then you will not be penalised, the key here is intention).
- Provide your MATB1 form from your midwife/GP confirming the expected due date. You can change your leave start date anytime as long as you let them know at least 28 days or as soon as reasonably possible before you intend to take the leave.
Any pregnancy-related illness will be classified as sick-leave until the 4 weeks before the baby’s due date. Any prolonged illness within 4 weeks of the baby’s due date will trigger the start of maternity leave. If you have sporadic sick days within those last 4 weeks, they can still be sick leave rather than triggering maternity leave but this is at the employer’s discretion.
If the baby is born prematurely, maternity leave will start on the first day of your absence or the day after if you were off sick when the baby was born. In the unfortunate event of a miscarriage or stillbirth; if this occurs after the end of the 24th week of pregnancy, the employee attracts the full maternity leave entitlement. If this occurs prior to the start of the 25th week then normal sick leave policies apply.
There are three “tiers” of maternity pay and leave going from most to least generous, and based on type and period of employment.
Tier 1: NHS Occupational Maternity Leave and Pay:
To access the NHS’ occupational maternity leave and pay, you must have at least 12 months’ continuous NHS service at the beginning of the 11th week before your baby’s due date.
For resident doctors, this can be across multiple NHS employers and does not have to be with the same NHS employer, per the 2016 Resident Doctors Contract. This must also be a substantive contract and not on a locum/bank basis.
Your “full pay“ rate of maternity pay is based on your average weekly income for the 8 weeks leading up to and including the 15th week before the anticipated week of childbirth. Your maternity pay will be determined using your past two payslips, which will then be converted to your total annual earnings. This will then be divided by 52 (the number of weeks in the year) to determine your average weekly earnings, since doctors are normally paid on a monthly basis. In the event that you receive weekly compensation, your maternity leave will be calculated using your average income over the previous eight weeks.
You are entitled to 52 weeks of leave and 39 weeks of pay (taxable):
8 weeks of full pay less any SMP or MA receivable (£194.32 Oct 2026)
18 weeks half pay (plus any SMP or MA receivable but no more than full pay
The above 26 weeks is known as ordinary maternity leave
13 weeks of SMP or MA
13 weeks unpaid
- The remaining 26 weeks is known as additional maternity leave
You don’t have to take the full 52 weeks but you must take the first 2 weeks of leave when your baby is born.
You can request for the pay to be divided over the full maternity leave period equally rather than in the way described above, if that will help you budget better.
If you have not been working on a substantive contract (i.e. exclusively working locum/bank) or don’t have sufficient continuous NHS service, you would still be eligible to claim Statutory Maternity Pay or Maternity Allowance.
Tier 2: Statutory Maternity Pay (SMP):
All employees have a right to take 52 weeks maternity leave under the statutory scheme. To qualify for SMP you need to be an employee with 26 weeks continuous service with your employer running into the 15th week before the expected week of childbirth. You can be either substantively employed or a locum, and you will likely meet the other eligibility criterion of earning a weekly average of at least £123.
If you are a resident doctor, then under the 2016 Resident Doctors Contract, the 26 weeks can be across multiple employers if you were under the Resident Doctors Contract for that whole period.
If you are a locum, SAS or Consultant, you will need to have all 26 weeks with the same employer.
SMP is paid for up to 39 weeks (taxable):
90% of your average weekly earnings (before tax) for the first 6 weeks
£194.32 (Oct 2026) or 90% of your average weekly earnings (whichever is lower) for the next 33 weeks
It’s worth contacting your HR department early as working SMP out when you’re a career locum is fairly challenging.
If you don’t have at least 26 weeks continuous service with your employer before the 15th week before the due date, you may be eligible for Maternity Allowance.
Maternity Allowance:
If you do not qualify for statutory maternity pay you may qualify for maternity allowance (MA) which can be claimed from JobcentrePlus. This might be your option if you’re self employed, recently stopped working or haven’t been working for your employer long enough.
You can claim MA once you’ve been pregnant for 26 weeks and receive payment for 39 weeks.
Payments can start any time between the 11th week before your baby is due and the day after the baby is born. To get the full amount that you’re entitled to, claim within 3 months of your Maternity Allowance start date
You will need proof from your employer that you are not eligible for SMP, they must provide you with an SMP1 Form within 28 days of you submitting your application to your employer for maternity leave.
The amount you receive is based on your personal circumstances.
Employed or recent employed:
£194.32 (Oct 2026) a week or 90% of your average weekly earnings (whichever is less) for up to 39 weeks. If you choose to take the maximum 52 weeks then the remaining 13 weeks will be unpaid.
Self-employed:
You can get between £27 to £194.32 (Oct 2026) a week for up to 39 weeks if you’re self-employed.
- How much depends on how many weeks Class 2 National Insurance contributions you’ve made in the 66 weeks before your baby is due. To get £194.32 (Oct 2026) per week you must have:
- been registered with HM Revenue and Customs (HMRC) for at least 26 weeks in the 66 weeks before your baby is due and paid Class 2 National Insurance contributions for at least 13 of the 66 weeks before the baby is due.
- If you’ve paid less than 13 weeks of contributions you’ll be entitled to £27 per week Maternity Allowance. You can top-up your contributions to increase your Maternity Allowance after you apply.
If you are a salaried GP:
The BMA’s Salaried GP Handbook sets out salaried GP’s legal entitlements. Some GP employers will offer occupational maternity benefits whilst others will not, meaning you will be entitled to Statutory Maternity Pay or Maternity Allowance (based on length of service).
If you are a self-employed GP:
As a self-employed person, you would need to apply for Maternity Allowance. Depending on the terms of your partnership agreement, you may still be entitled to payment if agreed by the other partners, however, this would be taxable as normal.
A GP practice can claim a payment from the PCN to cover the cost of hiring a locum to cover the parental leave.
VERY IMPORTANT: Disputes!
NHS Employers frequently get maternity pay entitlements wrong! If you believe, after reading this guide and understanding your entitlements, that your employer has got it wrong, please challenge them and ask them to explain their decision. If you are still not in agreement, you are entitled to contact the HMRC’s Statutory Payment Dispute Team, who will help you with working out what your entitlement is. There details are here: https://www.gov.uk/find-hmrc-contacts/statutory-payment-dispute-team
Useful Links;
https://www.bma.org.uk/media/6582/salaried-gp-handbook-updateoct2022.pdf
https://www.nhs.uk/pregnancy/finding-out/maternity-and-paternity-benefits-and-leave/
Paternity Leave
In order to be eligible, you must be the father, co-adopter, spouse, civil partner, or partner who resides with the kid in a long-term relationship, as well as the mother or adopter. Same-sex partners and spouses are included in this.
Like Maternity Pay, there are 2 tiers.
Tier 1: Occupational New Parent Support Pay and Leave:
You must have 12 months of continuous service with your NHS Employer before the 15th week before the due/adoption match date in order to be eligible for 2 weeks occupational new parent support pay and leave (paternity pay) on full pay minus Statutory Paternity Pay received. If you are a resident doctors, as long as you are under the 2016 Resident Doctors Contract throughout that period, changing employers part way through does not impact your entitlement.
You can choose to take one or both weeks, and can take the leave as one block or 2 separate weeks. Leave can only be taken after the birth/adoption and must be taken within 52 weeks of the birth/adoption.
As a statutory minimum, expectant dads or partners are entitled to paid leave in order to attend up to two prenatal or adoption appointments. Although an employer may choose to provide more, they are entitled to 6.5 hours per visit.
Tier 2: Statutory Paternity Pay and Leave:
If you don’t have 12 months continuous NHS service, then you may be eligible for Statutory Paternity Pay, as it’s likely you’d meet the earnings requirements. The statutory weekly rate of Paternity Pay is £194.32 (Oct 2026) or 90% of your average weekly earnings (whichever is lower). Any money you get is paid in the same way as your wages, for example monthly or weekly, and is taxable.
The requirements for Statutory Paternity Pay is:
To be employed by your employer for at least 26 weeks up to the 15th week before the due date
- Earn an average of at least £123 a week (before tax)
Paternity leave or pay is still available to you if your child is:
Stillborn at or after 24 weeks of gestation
Delivered alive at any stage of the pregnancy
If you do not meet the eligibility criteria above or are self-employed (e.g. a GP partner) then you are not eligible for paternity leave. If you pay yourself via PAYE (as a director of your own limited company), you may be eligible for statutory paternity leave and pay if you meet the eligibility criteria above.
Useful Links:
Adoption Leave
Adoption leave is very similar to maternity/paternity leave and it’s up to the couple who takes the prolonged parental leave and who takes the “paternity” leave. The same applies for those conceiving via surrogacy.
NHS Occupational Adoption Leave:
The main adopter/intended parent must have 12 months’ continuous service with one or more NHS employers by either by the beginning of the week in which you are notified of being matched with a child for adoption or the 15th week before the baby’s due date if applying via a surrogacy arrangement.
The adopter/intended parent must notify the employer of the intention to take leave in writing before the end of the week in which they are notified of being matched with a child for adoption, or by the 15th week before the baby’s due date if applying via a surrogacy arrangement. The notification should include the intended date of commencement of the adoption leave (amendable with 28 days’ notice).
They must also confirm they intend to return to work with the same or another NHS employer for a minimum period of three months after the adoption leave has ended and provide written confirmation from the placing authority of the matching decision or a parental statutory declaration that they intend to apply for a parental order in the case of a surrogacy arrangement.
The 39 weeks’ entitlements are the same for the primary parent as occupational maternity pay:
First 8 Weeks: full pay, less any Statutory Adoption Pay receivable (£184.03pw)
Next 18 Weeks: half of full pay, plus any Statutory Adoption Pay receivable, providing the total receivable does not exceed full pay (£194.32 Oct 2026)
Next 13 Weeks: Statutory Adoption Pay (£194.32 Oct 2026)
To extend parental leave to 52 weeks, the last 13 weeks will receive no pay.
The non-primary carer in the couple is entitled to New Parent Support Pay:
- 2 weeks of full pay less any statutory paternity pay (£194.32 Oct 2026) receivable.
Statutory Adoption Leave:
The adopter must have been continuously employed by the employer for at least 26 weeks up to any day in the week they were matched with a child or until the 15th week before the due date in the case of surrogacy.
The entitlements for the primary adopter/intended parent:
90% of their average weekly earnings for the first 6 weeks
£194.32 (Oct 2026) or 90% of your average weekly earnings (whichever is lower) for the next 33 weeks
For the non-primary adopter/intended parent:
- Two weeks of statutory paternity pay: the lower of £194.32 (Oct 2026), or 90% of your average weekly earnings
Useful links:
Shared Parental Leave
The introduction of shared parental leave (SPL) is a game-changer for couples. It allows for both parents to have an equal part in the first months of their child’s life. Shared parental leave allows both partners to take the maternity leave component either at the same time, one after another or transferred to the non-birthing parent following the first two weeks after baby’s arrival, which are mandatory. This means up to 50 weeks of leave and 37 weeks of pay can be shared
You do not have to take all of your SPL at once, you can take SPL in up to 3 blocks (minimum of 1 week) and return to work in between. If both partners are taking Shared Parental Leave, then you can have 3 blocks of leave each.
There are several ways the parental leave can then be shared, but importantly, it entails the primary parent “giving up” however much of their parental leave they wish for their partner to take.
Example 1:
Both parents want to split parental leave equally and take it at the same time, Birthing Parent (BP) is not eligible for occupational parental pay but (NBP) is::
BP and NBP take their first 2 weeks (compulsory for BP)
BP ends their maternity leave after the 2 compulsory weeks in writing and takes 25 weeks as SPL
NBP takes the remaining 25 weeks at the same time as BP
NBP is eligible for occupational parental leave, whereas, BP is eligible for SMP only.
Therefore, they split the leave so that NBP gets the maximum occupational parental leave (6 weeks full pay less any ShPP, 18 weeks half pay plus ShPP) and BP gets the Statutory Component (13 weeks ShPP and 11 weeks unpaid).
BP and NBP return to work after 6 months of parental leave
Example 2:
BP wants to take the first 3 months of parental leave and for NBP to take the rest. They are both eligible for occupational parental pay:
BP and NBP take their first 2 weeks (compulsory for BP)
BP then confirms they will return to work after 12 weeks in writing and NBP applies to take the remaining as SPL 8 weeks prior to their intended start date
BP, therefore, gets 8 weeks of full pay less SMP and 4 weeks of half pay plus SMP
NBP then takes over SPL and gets the remaining 14 weeks of half pay plus SMP, 13 weeks of statutory pay and 13 weeks of no pay.
Everyone’s situation is unique and you can come up with a plan that suits you and your family. It’s best to contact your Line Manager and HR department as early as you feel comfortable so they can tell you what you’re eligible for, to help you make your plans.
Useful links:
Neonatal Care Pay and Leave
Extended NICU or SCBU admissions should not have to eat into your previous parental leave. You and your partner may be able to get paid time off work if your newborn baby is premature or needs neonatal care.
What is “neonatal care”?
Neonatal care: care given to babies within the first 28 days after birth and can include:
Hospital-based care
Ongoing medical care following leaving hospital- this MUST be under a Consultant and include ongoing follow up at the hospital where baby was treated
- Palliative or hospice care
Eligibility:
For the leave: you must be classed as an employee (there are no minimum time/earning thresholds)
For Statutory Neonatal Care Pay: you must have been continuously employed by your employer for at least 26 weeks up to the end of the ‘qualifying week’ (the earlier of 15th week before the due date or the week immediately before the baby enters neonatal care). You must also continue to be employed up to the week before you want the pay to start and earn on average £129 a week (before tax) or more, over an 8-week period
What are the entitlements?
Leave: One week of leave for every 7 full consecutive days baby is in neonatal care- for up to 12 weeks
Pay: either £194.32 (Oct 2026) a week or 90% of your average weekly earnings (whichever is lower and taxable)
Are there any specific rules about when the leave is taken?
The leave must be taken before or at the end of your maternity/shared parental leave
You must take the leave within 68 weeks (just under 16 months) of your baby’s date of birth
Your employment rights are protected during this leave, just like maternity leave
You must give your employer notice- more details of when and how depend on when you are taking the leave*
*The details are quite nuanced so please familiarise yourself with this via the link below.
Useful links:
NHS Pension During Parental Leave and Beyond
Pay received during parental leave counts as pensionable and so pension contributions will be deducted from your monthly payments at the tier you were paying before your leave. Your occupational pay, statutory pay and pay during unpaid leave (if you’ve chosen to receive your payments over 12 months in equal instalments) will also be pensionable.
This means there is no interruption in your NHS Pension contributions and parental leave does not disadvantage you (as much). As you will be receiving less pay over the year than you would have been if you were still working, you will still take a hit to your pension entitlement calculation. This is because the 2015 NHS Pension Scheme calculates pension benefits based on average career earnings, therefore, the reduced earnings over the parental leave period will affect the end calculation.
Useful links:
Student Loan During Parental Leave
Student loan repayments are made at 9% for anything earned over the earning threshold for each plan. You will continue to pay your student loan based on your earnings and they will reduce as your income reduces over parental leave.
Parliament was recently asked if they would reduce interest rates for those on parental leave and sadly they said they would not (rude!).
The repayment thresholds for each plan are as follows:
Plan 1: £26,900 annually
Plan 2: £29,385 annually
Plan 4: £33,795 annually
Plan 5: £25,000 annually
- Postgraduate Loan/Plan 3: £21,000 annually
Therefore, if your pay during your parental leave exceeds the respective threshold for your plan, you will repay 9% above the threshold to cover your student loan.
Useful links:
Subscriptions and Membership Fees During Parental Leave
You can access reduced subscription and membership fees over parental leave and it’s worth checking with your Royal College and specialty-specific societies about what discounts they offer for members on a career break. Remember, you can still claim tax relief on all these fees!
GMC:
There isn’t a specific parental leave policy but if your annual income falls below the income thresholds that result in discounted rates then you are entitled to the reduced rate. From April 2026, an income of £38,500 or below attracts a 50% discount to your annual fees. This link below explains how to claim if your parental leave straddles two registration years. If you are still receiving the Fixed Term Discount (within 4 years of Full Registration) then you cannot receive another type of discount as well.
Royal College Examples:
The Royal College of Physicians offers a 50% discount on membership fees where you still have access to all benefits, alternatively, you can choose to pause your membership but relinquish access to benefits for that period. The Royal College of Surgeons waives membership fees for members on parental leave. Find out if your Royal College offers a reduced membership fee.
BMA:
The BMA offers a reduced membership fee of £17.25 per month (Oct 2026) for members on parental leave.
Medical Defense Organisations:
As each quote is tailored to your working patterns, specialty and additional activities, there is no clear information online of what reduction is applied to individuals on parental leave. There is definitely a reduction as you will be doing much less work. You will need to contact your own defense organisation and discuss your personal circumstances to find out what reduction you’re entitled to.
ASIT:
Members on parental leave will be offered a 6-month suspension of their subscription fees during parental leave but still have access to their usual benefits.
Useful links:
Can you Locum During Parental Leave?
During the paid portion of your parental leave, it is possible to work as part of 10 “keeping in touch” days. However, these are to be pre-arranged with your department and are paid at your usual substantive rate.
During the unpaid portion of your parental leave, you can locum as much as you want*. If you are using shared parental leave, then whoever is not being paid the parental leave can locum as much as they like. You can also locum on days where you’re supplementing your parental leave with annual or unpaid leave.
* We contacted the HR department at a large NHS Trust to confirm this information
Child Benefit and Pension Credits
You can receive child benefit for raising a child until they are aged 16 (or 20 if they remain in approved full-time education). Only one person can receive child benefit for each child, however, there is currently no limit to the number of children you can claim child benefit for.
Child benefit is paid as a 4-weekly allowance and provides your child with a national insurance number (without them having to apply for one), which they’ll receive just before they turn 16. You also get National Insurance Credits towards your State Pension. These are useful because being on unpaid parental leave or not working because you are raising your children full-time means you won’t pay enough National Insurance Contributions to count towards your State Pension. These credits act to fill these gaps (up to the child’s 12th birthday) so you don’t miss out on your State Pension. I’d recommend having a look at the links above as they also explain how you can transfer these credits to other family members.
Child benefit is paid in two tiers:
A weekly rate of £27.05 (Oct 2026) for the eldest child
A weekly rate of £17.90/child for subsequent children
There are some nuances in families who split or combine.
The eligibility is based on parental income and a High Income Child Benefit Charge becomes payable if either the parent or their partner’s individual net adjusted income goes above £60,000. You will never be charged more than you have been paid and the charge tapers up until you receive no child benefit by £80,000. Even if you’re not going to qualify for child benefit because of an individual income of £80,000 or more, it’s still worth applying and opting out of payments so you can take advantage of the National Insurance Credits (if there’s going to be a period of one parent being low or unpaid).
Tax-Free Childcare
There are extensive eligibility criteria that most doctors are likely to meet. However, the main one that might be a snag for some is the £100,000 adjusted net income limit. If one of the parents of the registered child is likely to earn over £100,000 in a given tax year, they are not eligible to receive tax-free childcare.
Tax-free childcare is a bit of a misnomer, it’s more like tax-efficient child care. You can get up to £500 every 3 months (up to £2,000 a year) for each of your children to help with the costs of approved childcare. This goes up to £1,000 every 3 months if a child is disabled (up to £4,000 a year).
To access this service, you need to register for an online childcare account (this link provides a step-by-step guide). Then for every £8 you put in, the government tops it up by £2. This money must then be used to pay for an approved childcare provider (childminders, nurseries, after-school clubs and play schemes registered with OFSTED).
Children stop being eligible from the 1st of September following their 11th birthday (or 16th birthday if they are disabled). Only one parent needs to register the child, both parents cannot have an account as each child is only eligible for one account. Given how expensive childcare is, it’s worth trying to keep on the lower side of £100k if you’re borderline.
If you have not spend all the money accrued in your Tax Free Childcare account by the time your child is no longer eligible, you still have 2 years to spend the money. Any unspent money that you deposited is returned to you and the government takes back their contribution.
Another note about childcare, places are limited as the cost of living crisis has forced many centres to close. We would suggest looking to get your name down on a wait list in the first trimester to ensure you aren’t struggling to arrange suitable childcare when it comes the time to return to work. Nurseries on hospital sites or near universities are highly oversubscribed, therefore, planning this early can save a lot of headaches later.
Funded Childcare Hours for Working Parents
Working parents can apply for 38 weeks of 30 hours of government-funded childcare for children from age 9 months to 4 years
Who is eligible to apply?
Both parents need to be “working” to be able to access the 30 funded hours
If parent(s):
Are in work or about to start a new job
On sick, annual, parental, adoption, or neonatal care leave
Immigration status means you are allowed to access public funds
If you don’t meet any of these criteria then everyone is entitled to 15 government-funded hours of childcare for 3 and 4 year olds.
- Earning requirements for both parents by age: I’ve included this not just for those who are doctors thinking about this but that you may have relatives who would benefit.
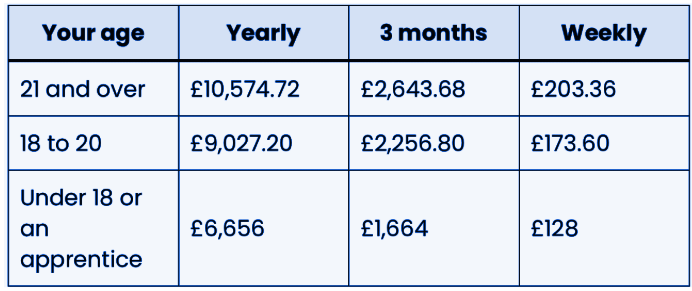
- If one person in the parent partnership is earning an adjusted net income of over £100k then they are no longer eligible to claim this.
When can you apply?
If you’re on any type of parental leave then your application window is based on when you will be returning to work (both parents):
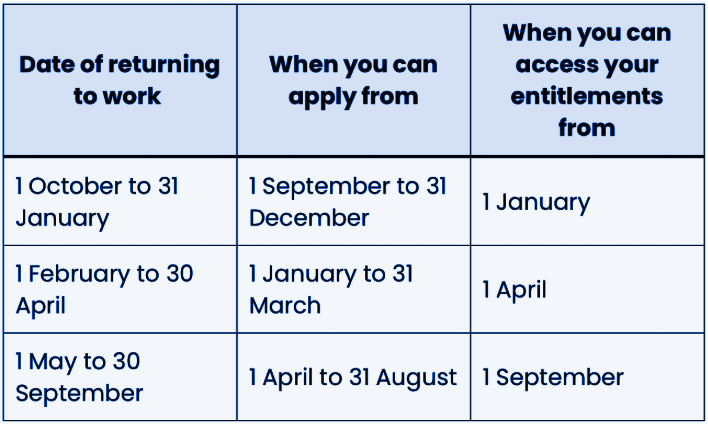
If you are on paid annual leave and receiving your salary as normal, this counts as having returned to work for the purposes of eligibility for the working parent entitlement.
When do the funded hours kick in?
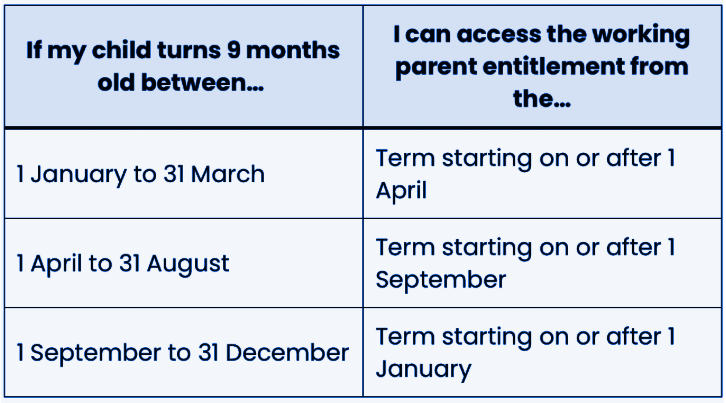
This one is a real pain, especially if you have to unnecessarily wait 3 whole months because of an arbitrary cut off!
The funded hours kick in the term AFTER the child turns 9 months old:
Where can the funded hours be applied?
Providers that accept the funding (usually OFSTED-registered)
NOT nannies, home carers or relatives
Funding does not cover:
meals
nappies
additional hours
- additional activities, such as trips
What about outside term-time?
Some providers are term-time only whilst others are open all-year round and will allow the hours (30hrs x 38wks = 1,140 hours) over the entire time they’re open.
Choose a provider that meets your needs and start looking around early!
Useful links:
Working Less Than Full Time
Working LTFT isn’t as much of a hit on your finances as you might initially think! Definitely crunch the numbers first as you might be surprised how much you actually save in tax, student loan repayments and transport costs. I love Mind the Bleeps Resident Doctor and Consultant pay calculators.
You might be looking to work less than full time given child-rearing is a full-time job in itself! You can request to work less than full time under the NHS’s Flexible Working Initiative and your employer must make all reasonable steps to accommodate this. They must be able to justify (which is very difficult) why they cannot offer you Less than Full Time working. Working less than full time is not always as simple as scaling down your rota and pay by a percentage amount. It can be complicated and individualised depending on the rota arranged.
LTFT Allowance
All LTFT trainees will be paid an annual allowance of £1,000 for as long as they continue to train less than full time basis. Trainees will receive the full £1,000 regardless of their LTFT percentage. This payment is usually split equally over 12 months.
Basic Pay
Basic pay is scaled pro-rata. So, if you work 80% of full time you will receive 80% of the basic salary of a full-time trainee on the same rota.
For example, a full-time trainee has a basic salary of £32,000 based on an average 40 hours a week. Their work schedule has them working 45 hours. A LTFT trainee works 27 hours a week on average. This means that they are 60% of FTE (27/45). As such their basic pay will be calculated as 60% of £32,000 = £19,200.
Weekend Allowance
The weekend allowance is paid to LTFT trainees on a pro-rata basis, based on the proportion of the full-time commitment to the weekend rota they make. It is NOT based on your LTFT percentage. So, if full-time trainees on your rota work 1 in 4 weekends and a LTFT trainee works 1 in 8 weekends they would be entitled to 50% of the weekend allowance that the full-time trainee receives. If another LTFT trainee on this rota works 1 in 4 weekends they are entitled to 100% of the weekend allowance regardless of their LTFT percentage.
On-call Availability Allowance
The LTFT on-call availability allowance is the same as for the LTFT weekend allowance. LTFT trainees will be paid the on-call availability allowance pro-rata, based on their commitment to the full-time rota. It is NOT based on your LTFT percentage.
Nights Enhancement
LTFT doctors will be paid a 37% enhancement on top of their hourly rate, for nights. This works in the same way as for full time trainees.
Flexible Pay Premia
The 2016 Junior Doctors Contract specifies that where flexible pay premia are payable to LTFT trainees, they will be paid pro-rata to the agreed proportion of full-time work. This includes flexible premia for GP trainees and hard to fill training posts. So, if you work 70% of FTE you will receive 70% of the flexible pay premia.
London Weighting
London weighting for full-time doctors (40 hours per week) is £2,162 per annum for inner London. LTFT doctors receive London weighting pro-rata as a proportion of 40 hours, depending on how many hours they work.
Pensionable Pay
All hours worked up to 40 hours per week are pensionable. As such, all the hours that LTFT trainees work will be pensionable as LTFT trainees cannot work more than 40 hours per week on average (excluding locum work).
Maternity Pay
If you are eligible for maternity pay, it is based on your average weekly earnings, averaged over a period of at least eight weeks up to and including the last payday before the end of the qualifying week. Working LTFT does not affect this as your average pay is calculated using your actual received pay for these weeks. (see section on maternity leave and pay)
Transitional Arrangements
If you are not on the 2016 contract and you are transitioning to the 2016, you may be eligible for transitional pay protection. This transitional pay protection is valid for four years. However, doctors who are LTFT will have the four-year transition period extended in proportion to their LTFT percentage. Changing LTFT percentage during this period will alter your individual transition end date. There is more information and a useful calculator on the NHS Employer website listed in the references.
Locum Work
You may undertake locum work as a LTFT trainee. However, additional work must not be undertaken during periods of absence for study or sickness. It is worth considering that repetitive additional work may lead to a review of your LTFT training schedule and eligibility with your training program director.
Useful links:
https://www.nhsemployers.org/publications/less-full-time-medical-trainees-guidance
https://www.hee.nhs.uk/sites/default/files/documents/LTFT%20FAQ%20Final%20.pdf
https://www.bma.org.uk/pay-and-contracts/pay/ltft/less-than-full-time-trainees-pay-explained
https://www.copmed.org.uk/images/docs/publications/Guidance_on_Undertaking_Additional_Work_.pdf
Useful Financial Products to Explore For Your Children
Long-Term Savings:
Junior Individual Savings Accounts (ISAs)
A Junior ISA is an account in which any interest, dividends and capital gains are tax free. You can have a Cash Junior ISA in which you would earn some interest, however, cash is eroded by inflation and interest rates aren’t usually inflation-beating. A Stocks and Shares Junior ISA would mean the savings are invested (there are lots of providers that can manage the investments or you can choose your own investments. This does mean the capital is at risk, however, if well diversified and selective of lower risk investments, these savings can compound with interest, dividends and growth to be inflation-beating. The child must be under 18 and living in the UK. You can deposit up to £9,000 (2024/25) per child, per year in either cash or stocks and shares or both. The child takes control of the money when they’re 16 years old but cannot withdraw the money until they are 18 years old.
Junior Self Invested Personal Pension (SIPP)
For a child under 18, you can open a Junior SIPP, a tax-efficient pension. You can deposit a maximum of £2,880 in each tax year, which the government tops up by 20% (turning your maximum deposit into £3,600). By starting much earlier than when your child will eventually start working, you help them build up a pot for their retirement, taking advantage of compound interest along the way. You control the investments until your child turns 18. They could either choose to manage their account or leave it alone. Just by leaving the capital that’s built up in the SIPP, the dividends, interest and capital gains will compound to increase the pot’s value over time. These gains are also tax free. You do not declare your contributions on your self-assessment tax return as the tax relief is your child’s, not yours.
Investing little and consistently adds up over time. For example, you deposit £125 when your child is born. This is topped up to £150 (20% basic-rate tax relief). If the pension investments grow by 5% every year (illustrative purposes only). The child pension pot would be worth almost £47,000 by age 18. Even if no more deposits were made, the pension could be worth over £290,000 by age 65. This assumes annual charges of 1% and an assumed growth of 5% each year. You need to check what your annual charges are and how your investments are performing.
Please note, investments carry risk and they can fall and rise in value, so your child could get back less than you invest. These are just examples. The actual amount your child gets could be more or less than this. The figures above don’t take into account inflation, which reduces the spending power of money over time.
Managing Money:
Everything’s digital these days and kids aren’t used to carrying around cash. Most grown ups don’t carry cash either, so helping kids learn how to safely use a debit card is more important than ever. There are lots of child and teen bank accounts available, from usual high-street banks to online banks. They provide helpful benefits, such as being able to monitor where your child uses their card, freezing the card in case of loss/theft, limiting daily spend and topping up their account. Some are free if you have an adult current account with the same providers, others charge a fee.
Educating Your Children About Money
Role Modeling:
Children who don’t see good role-modeling when it comes to managing money aren’t going to magically be great with money when they become adults. So it all starts with you and making sure you’re good at managing your money! Demonstrate saying “no” to impulse buys, sticking to a budget and paying your savings first.
Earning their Pocket Money:
A caregiver’s role is to meet all the needs of their child, so technically they shouldn’t need any pocket money. Pocket money is for them to spend on their wants. Separating needs and wants and providing opportunities for children to earn their pocket money for their wants helps children feel empowered. They understand the value of their wants and that it isn’t just a case of asking for something and just getting it. Just like how we can classify the cost of something based on hours worked, children can understand cost based on jobs or chores done. Set out age-appropriate jobs and/or academic or sporting achievements with agreed rewards so kids can associate effort with value. This also helps them understand that if they are willing to put in the effort, they can work towards any of their wants, helping them exercise delayed gratification.
Use Online Banking for Cash Gifts:
Ask friends and relatives who want to buy gifts for your children to gift the majority of their intended gift value directly to the kids’ savings accounts and only gifting one item. Bonus points if this is a Stocks and Shares Junior ISA! Year on year you can go through the lovely messages in the payee references and help your children watch their money grow. With compounding, that gift will be worth much more overtime and you have the benefit of not accumulating clutter. By limiting the number of gifts being received, you can help your kids manage their gift expectations, making birthdays and Christmases a less stressful time.
Practice What You Preach:
When kids ask for things as an impulse (think Aldi middle aisle), practice saying “I’m sorry, that’s not in our budget”. You can even budget for an impulse buy to make things fair (e.g. £2 per child). You need to demonstrate saying this out loud to yourself too. For example, you might see a nice plant pot, but it’s not in your budget, say out loud “Oh nevermind, that’s not in our budget” and put it back. You could put it in your budget for next time and have it on the list if you still want it, however, you might find after a 24hr cooling off period, you don’t really need it anyways.
Reward Your Kids for Saving:
You’ll have to credit my dad with this one, it’s rather avante garde. Reward your kids for saving their pocket money by paying them interest. This not only teaches them what interest is and how it works, but also makes saving rewarding for them. My dad used to give us 3% interest on our savings (because there are 3 of us… it was pretty arbitrary). We learned about saving, how to calculate percentages, rounding and compounding just by this little monthly exercise of my dad adding a few extra pennies to our money boxes.
Books you might like (no ads or affiliations- just information):
Just Saving My Money by Mercer Mayer (for kids 6 and under)
Spend it! and Save it! By Cinders McLeod (for kids 4 and under)
The Four Money Bears by Mac Gardner (for kids 7 and under)
Lily Learns About Wants and Needs by Lisa Bullard (for kids 7 and under)
Curious George Saves His Pennies By Margaret & H. A. Rey (for kids 4 and under)
Will, Life Insurance, Critical Illness Cover and Income Protection
Consider your family’s total monthly outgoings including utilities, food, mortgage payments and everything else. If the worst was to happen and you became seriously unwell, unable to work or unexpectedly passed away would your family be able to meet these outgoings? Without a will, life insurance and income protection, the answer for most people is no. As medics we are regularly exposed to people in these circumstances and understand the importance of preparing for the worst.
Wills:
All adults should have a will. A will helps your family access your assets without having to go through the long process of probate. If you are a home-owner, it’s definitely worth having a will. Putting your assets into a trust with your children or next of kin as the beneficiaries means they can have an easier time sorting the logistics after you’re gone. You can nominate advocates for your children to manage the process for them if they’re too young.
Many Trusts include free will writing as part of their employee assistance programmes and the Medical Womens Federation also provides a free will writing service to its members.
Life Insurance:
If you have a mortgage and/or children, it’s highly advisable to arrange life insurance. The earlier in your adult life it’s arranged, the cheaper it will be, as life insurance premiums are based on age, certain lifestyle factors and comorbidities. We accumulate comorbidities as we age and some very common ones can prevent us from being eligible for life insurance. Leaving life insurance until later means you take the risk of not being able to have the insurance at all. Make sure your life insurance covers the value of your mortgage as that is likely to be the biggest burden on your family.
Speaking with an independent, all-of-market Financial Advisor can help you identify the best products for you. You can access a good Financial Advisor familiar with dealing with doctors via the Medics Money website.
Critical Illness Cover:
In the event of a severe injury or illness that leaves you unable to work, critical illness cover awards you a lump sum to help. It’s advisable to cover your mortgage value at least, so you can focus on recovering. The same factors apply as above; age, lifestyle and comorbidities. Again, leaving it too late could mean you might not even be eligible.
Income Protection:
If you’re working as a locum, you’re not entitled to sick pay. In an NHS substantive contract, you receive 1 month full and 1 month half pay, increasing by a month respectively with every year of service up to a maximum of 6 months full pay and 6 months half pay. Income protection pays out in the event of any illness to make up for shortfalls in pay when you’re receiving half pay or less. It’s a very handy cover to have as it covers short periods of illness/injury where you will likely recover after a few months and return to work. The same applies regarding being cheaper if you’re younger, with fewer comorbidities.
Have a chat with an independent financial advisor about which combination of cover is most appropriate for your personal circumstances. With or without cover, please consider building a healthy emergency fund that would cover 3-6 months of all your expenses in the event you were unable to work.
Pet Insurance
We can’t forget our other family members, our beloved pets. Insurance can be a lifesaver when it comes to unexpected illnesses. Veterinary services can easily reach £1000s and having good pet insurance is vital. The complexity with pet insurance is when your pet acquires a medical history. It is difficult insuring pets with pre-existing conditions and once they’ve had a condition, it’s very difficult to switch between insurers.
The best time to arrange insurance for your pet is when you acquire them. Whether adopting a puppy or rescuing an older dog, the sooner you can arrange their insurance, the more ahead of any future medical conditions you are. If you leave it too late and they’ve got something on their health record, it can be more difficult and expensive to get the cover you need.
Types of Cover:
Lifetime Cover Policy
Most comprehensive level of cover as they will payout continuously (subject to annual limits) for the pet’s treatment over their lifetime
The premium is based on the annual limit you choose, the pet’s age, breed and prior health conditions
The premiums remain the same over the pet’s lifetime regardless of how many times you claim (the will increased with inflation/tax and there may be an excess payable)
You can get a per-condition, per-year cover that pays out an agreed limit for treatment of a particular condition (e.g. max £2,000 per year on hypothyroidism treatment).
There are also policies that can be a mix of both, so a total annual limit with an annual limit for a particular condition included (e.g. £5k annual limit with £1k limit on diabetes treatment)
If you can afford to get lifetime cover, it’s highly recommended.
Non-lifetime Cover Policy:
Much less comprehensive and results in exclusions for certain conditions after the claims limit for that condition is reached.
Two main types:
Per-condition: pays a limited amount for each condition and, once that limit has been reached, the insurer stops covering it.
- Time-limited cover: consists of both a monetary and time limit, usually 12 months from ythe beginning of the claim, then the condition is excluded.
Accident-only Cover Policy:
No cover for illnesses, just for injuries
The insurer would pay a fixed amount for each accidental injury to help towards treatment and will likely stop paying for the injury after 12 months.
Cheapest of the 3 types of cover.
Generic Components:
A policy may include some or all of these components but they’re worth looking at. We had no idea we had travel disruption cover in our insurance and it was a huge help. We also got unlimited access to a vet on video call, which we initially didn’t think we’d use, but it has been useful in reducing our vet fees as a form of triage.
Vet fees
The integral component, most policies cover the cost of vet fees and certain medical expenses, ranging from £1,000 to £18,000.
Make sure you check HOW they cover these fees, some policies have a limit for each expense (e.g. fluids/antibiotics/admission) and you need to cover the rest, others just have a blanket cover of what you’re charged by the vet.
Death:
You can claim the cost of your pet or a fixed amount based on the policy in the event your pet passes away due to illness or injury
Most policies set a maximum age at which you can claim, usually between 5 to 8 years of age.
Dental cover:
Just like for us, dental problems can significantly impact your pet’s quality of life
Most policies will have some form of dental cover, usually for injuries rather than gum disease
It’s worth making sure your pets receives regular dental checks as this can save you significant costs down the road
If pet is lost or stolen:
In the awful event your pet is lost or stolen, you can claim costs for putting up posters and offering a reward
Many policies will also pay out a fixed amount, usually based on the cost of your pet, in the event you are unable to recover your pet
Virtual veterinary access:
Many policies will offer a virtual vet service where you can make an appointment to have a video call with a qualified vet at no extra cost
This is handy if you’re a first-time pet owner
Third party liability:
- If your pet were to sadly injure someone or cause damage to another’s property, the policy covers legal costs, expenses and the claimant’s expenses.
Overseas travel:
Cover for illness or injury while your pet is abroad
Some policies may cover transferring your pet back home if you trip needs to be cut short due to their illness or injury
Boarding fees:
If you are hospitalised for more than 48hrs, and there is no one else who can look after your pet, this cover would pay for approved boarding
Euthanasia, cremation and burial:
- The policy may cover the some or all of the costs of putting your pet to sleep, cremation or burial
If travel is disrupted:
Cover for lost travel and accommodation costs if you’re forced to cancel a holiday because your pet becomes severely ill when you’re due to leave.
- The policies will stipulate the timeframe within which the event and cancellation take place
If you choose not to insure your pet, it’s advisable to have a sinking/emergency fund for pet-related emergencies. We chose to insure our pet because we get a lot of useful features from our insurance, such as free virtual veterinary consultations. We recently had to use our pet insurance and we’re so glad we had it. We didn’t realise, but it also covered travel disrupted by our pet’s sudden illness within a certain time frame. We couldn’t have been more pleased with our insurance.